Adult Canadians do love online gambling. Roughly 64% of Canadian adults gamble in some form, and close to 19 million now play online. The market took in about CA$4.2 billion in 2024 and is tipped to reach CA$5.7 billion by 2029. The real story of the past four years, though, is less about the totals and more about who is allowed to take those bets. This page looks at how Ontario’s 2022 decision to open its market reshaped Canadian online gambling, what players choose, and why the rest of the country is still split on whether to follow.
Online Casinos vs. Sports Betting
One of the most evident recent trends in the Canadian online gambling market is an increase in online betting in general and in sports betting, in particular.
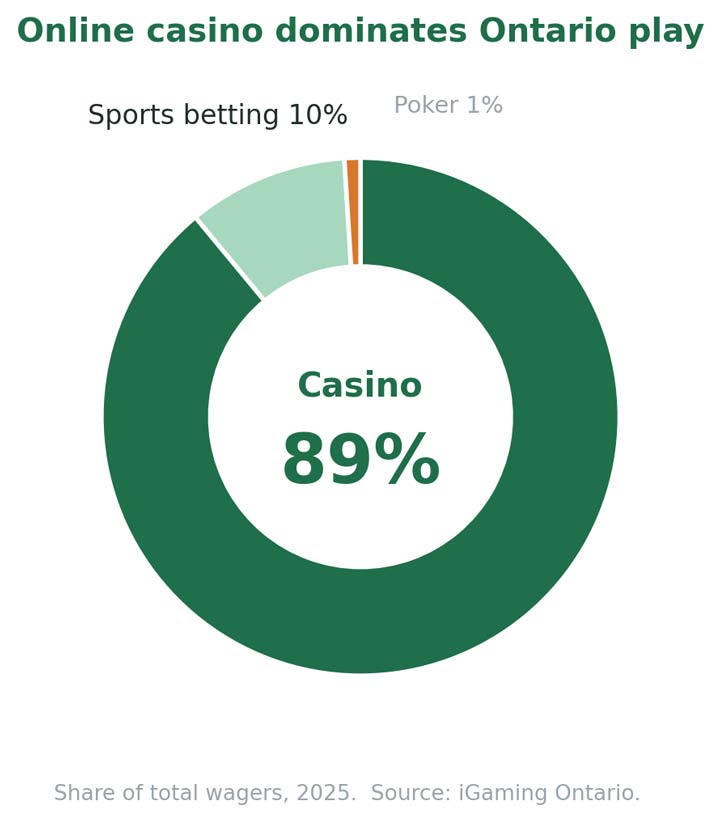
With a few years of regulated figures in hand, there is no need to read search trends anymore. In Ontario, the one Canadian market that publishes detailed data, online casino is by far the bigger draw. It takes around 89% of the money wagered, with sports betting near 10% and poker making up the rest. Sports betting did jump after Canada legalised single-event wagering in 2021, but it is casino games, led by slots and live tables, that players reach for most.
The entire Canada’s growth of interest in online betting can be easily explained by the launch of the legal Ontario online gambling market on April 4, 2022.
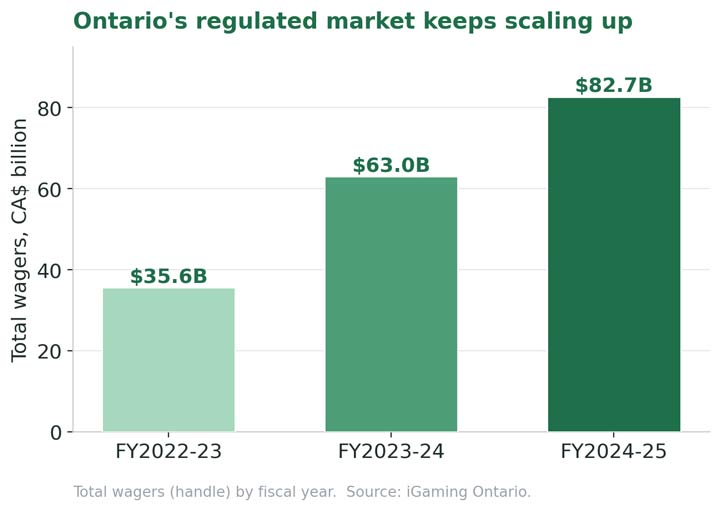
Four years on, that launch looks like a turning point for the whole country. Ontario became the first province to run a competitive market where licensed private operators could compete beside the government’s PROLINE+, and the scale today is hard to overstate. In its 2024-25 fiscal year the market counted 50 operators, CA$82.7 billion in wagers and CA$2.9 billion in gaming revenue from 2.6 million active accounts. Across the 2025 calendar year players staked close to CA$100 billion and operators booked just over CA$4 billion, up 34% in a single year, pushing total revenue past CA$10 billion since launch.
Ontario’s Regulated iGaming Market (2025)
| Indicator | Figure |
|---|---|
| Licensed operators | 50, running 80+ gaming sites |
| Total wagers, 2025 | CA$100 billion |
| Gaming revenue (NAGGR), 2025 | CA$4.0 billion (+34% year on year) |
| Active player accounts | 1.3 million (December 2025) |
| Online casino share of wagers | 89% |
| Revenue since the April 2022 launch | over CA$10 billion |
| Province’s 20% share, 2025 | CA$807 million |
Source: iGaming Ontario.
The framework grew up alongside the numbers. The Alcohol and Gaming Commission of Ontario (AGCO) registers operators and writes the rules, while iGaming Ontario runs the market and holds the player agreements. In May 2025 iGaming Ontario became a stand-alone provincial agency, with oversight moving to the new Ministry of Tourism, Culture and Gaming. Players must be 19 or older, and every site has to offer deposit limits, time-outs and a link to the ConnexOntario helpline.
Tighter Rules on Advertising and Enforcement
The volume of online gambling advertising, that Canadians are being subjected to, has had a tremendous increase recently. This can be explained, on the one hand, by the flood of offerings that followed a change to federal law that made single-event sports betting legal in August 2021, and Ontario’s opening of its market.
The early ad rush became a political problem, and the rules tightened in response. Since 28 February 2024, AGCO standards ban the use of athletes, active or retired, and of celebrities likely to appeal to minors, in iGaming advertising, with the only exception being responsible-gambling messages. That ended the era of campaigns fronted by names like Wayne Gretzky, Connor McDavid and Auston Matthews. Operators still cannot push bonuses, credits or other inducements in public advertising, only on their own sites or directly to players who have agreed to receive them. Through 2025 the AGCO also stepped up action against unlicensed operators still chasing Canadian players.
Those first fines, handed to BetMGM, PointsBet and DraftKings over inducement and advertising breaches in 2022, now read as the opening round of a much firmer enforcement regime rather than one-off events.
Private Operators vs. Provincial Sites
The deeper divide is no longer between players, but between provinces. Ontario stands alone as Canada’s only open, competitive market, where private brands such as bet365, FanDuel, DraftKings and BetMGM compete with the government’s OLG. Almost everywhere else, online gambling is still a government monopoly, which is why so many Canadians outside Ontario continue to drift to offshore sites. That is starting to change. Alberta, frustrated that its PlayAlberta monopoly captured only a slice of the market, passed the iGaming Alberta Act in 2025 and opens a competitive market modelled on Ontario’s on 13 July 2026, with dozens of operators already in the queue.
Who Runs Online Gambling, by Province (2026)
| Province or region | Market model | Where you legally play |
|---|---|---|
| Ontario | Open and competitive | Private operators via AGCO and iGaming Ontario, plus OLG |
| Alberta | Opening up from 13 July 2026 | Alberta iGaming Corporation model, alongside PlayAlberta |
| British Columbia and Manitoba | Provincial monopoly | PlayNow (BCLC) |
| Saskatchewan | Provincial monopoly | PlayNow (BCLC) and SIGA |
| Quebec | Provincial monopoly | Loto-Québec / Espacejeux |
| Atlantic provinces | Provincial monopoly | Atlantic Lottery (ALC) |
| Territories | No local platform | Offshore sites only |
Source: provincial regulators.
Quebec is the firmest holdout. Through Loto-Québec and its Espacejeux platform it allows no private licences and has said plainly it will not copy Ontario, yet a 2024 poll still found about 81% of Quebec’s online gamblers using the official site. British Columbia and Manitoba share PlayNow, run by the BCLC, while the Atlantic provinces pool their efforts through the Atlantic Lottery. In the territories there is no local platform at all, so players simply use offshore sites.
Betting on eSports
Esports betting has moved from a curiosity to a standard line on the menu. Ontario’s licensed sportsbooks now take wagers on titles such as Counter-Strike, League of Legends and Valorant alongside hockey and football, and interest skews young, with under-35s by far the most likely to bet on a match. It remains a small share of the overall handle, but it is one of the faster-growing corners of the market.
To explain it well, eSports is a type of competitive video gaming where players, who are, as a rule, professionals, compete in an organized tournament. Competitive gaming is now seen as a sport with its own competitions taking place in various countries.
Since sports betting has become increasingly popular in Canada, eSports betting is expected to follow the same trend within the next several years, as calculated by many industry observers.
